
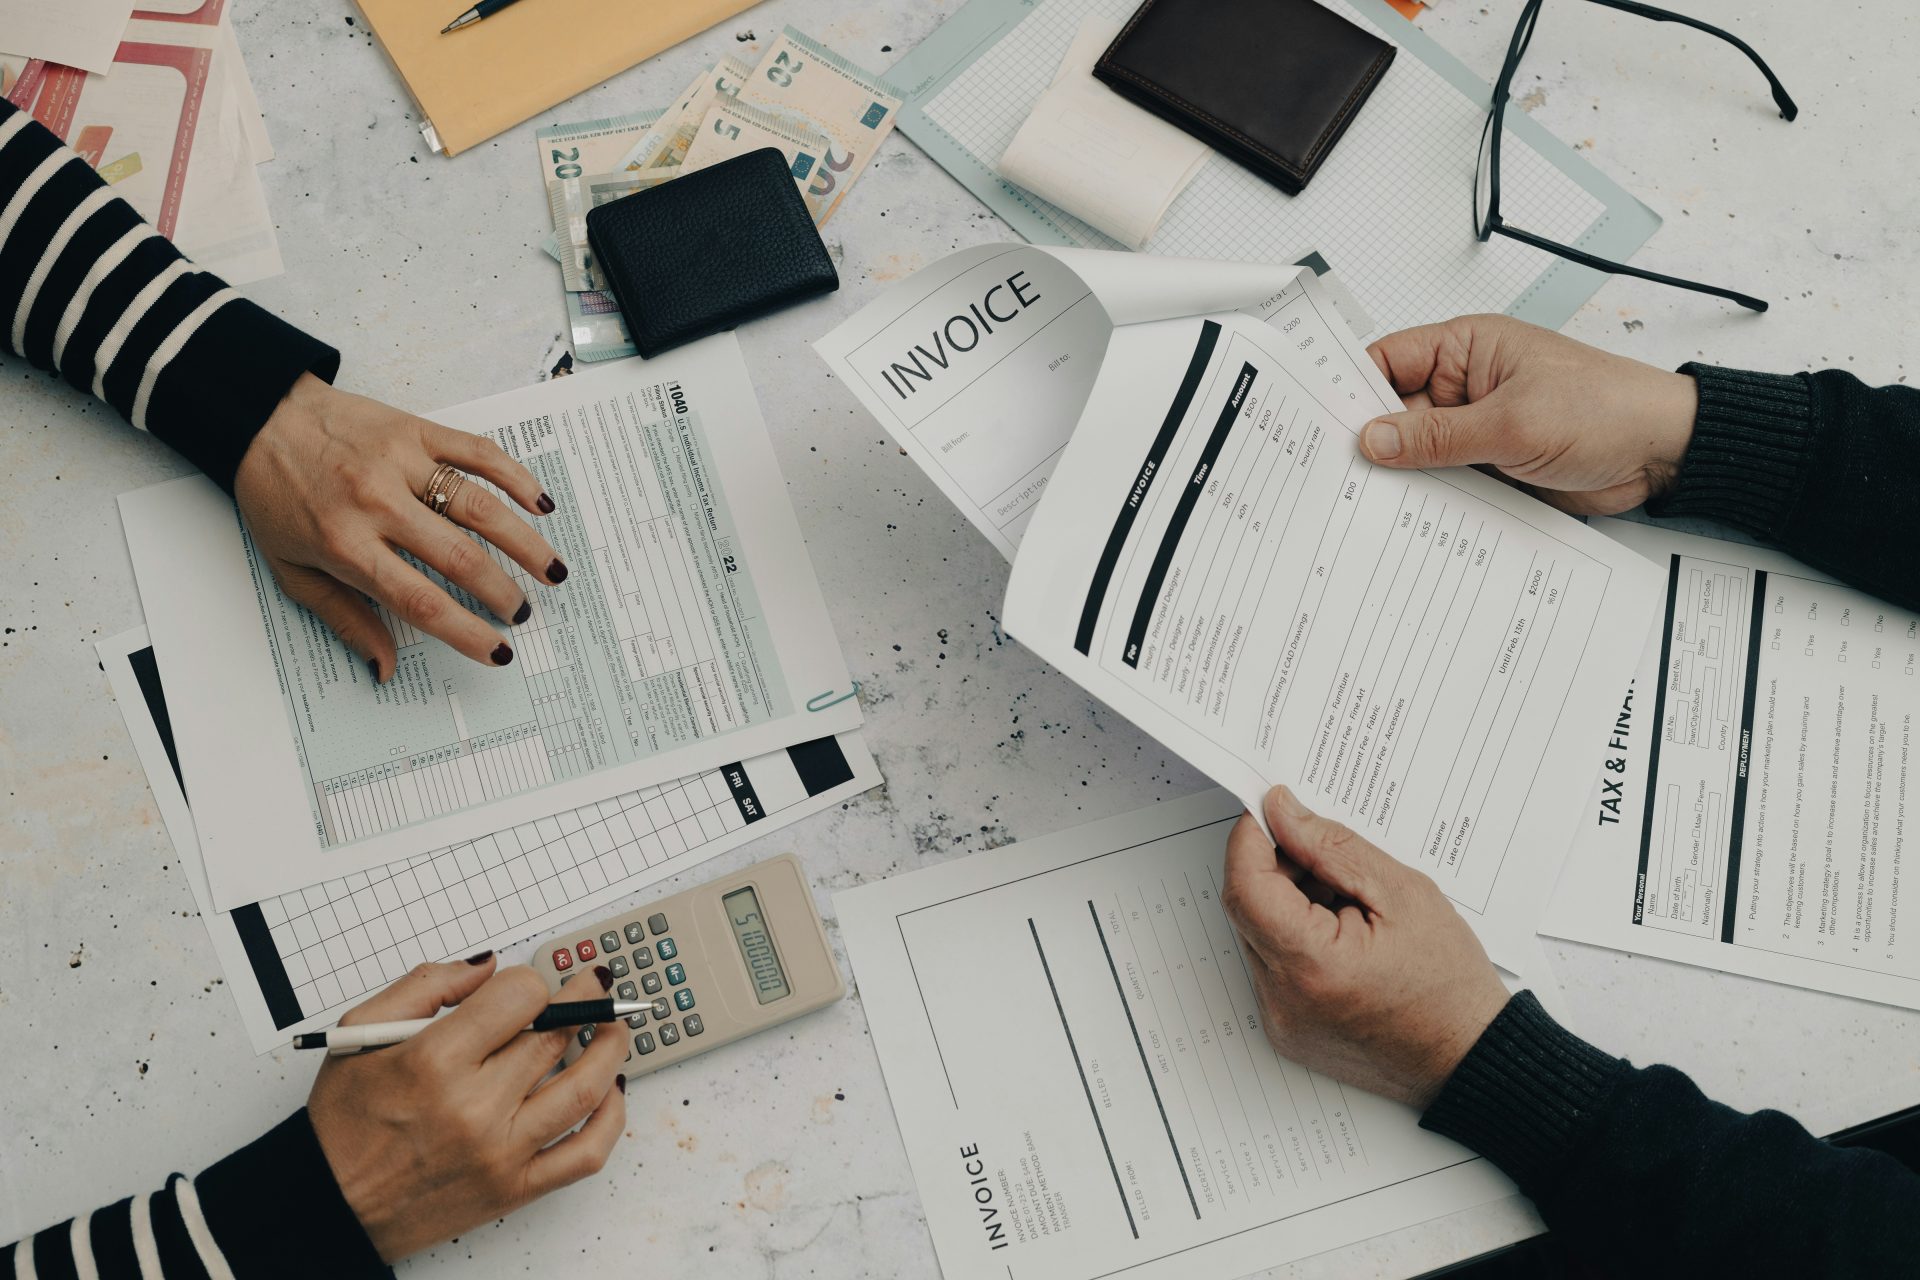
Running a small business is exciting, but handling the money side of things? Not so much. A lot of small business owners start with a great idea, but they don’t always have a solid plan for managing their finances. And that’s where problems start. From cash flow issues to tax mistakes, even small slip-ups can cause big headaches.
So why do so many small businesses struggle with money? And, more importantly, how can they fix it?
Mistake #1: Ignoring the Numbers
A lot of business owners focus on making sales but don’t pay attention to what’s happening behind the scenes. They might not track their income and expenses carefully, or they just assume that if money is coming in, things are fine. But that’s not always true.
If you don’t keep an eye on your numbers, you might be spending too much, undercharging for your services, or even missing unpaid invoices. It’s easy to fall into a cycle where there’s never enough cash, even if the business looks successful on the outside.
Fix it: Set up a system to track your finances. This doesn’t have to be complicated. Apps like QuickBooks, FreshBooks, or even a basic spreadsheet can help. The key is consistency—checking your numbers often so you always know where your business stands.
Mistake #2: Not Planning for Taxes
Taxes aren’t fun, but ignoring them won’t make them go away. A lot of small business owners don’t set aside money for taxes, and when tax season rolls around, they’re hit with a huge bill they weren’t expecting.
Even worse, some businesses try to handle their own taxes without really understanding the rules. That can lead to mistakes, penalties, and even audits.
Fix it: Work with a professional accountant who understands small businesses. They can help you plan ahead, figure out what deductions you qualify for, and make sure you’re following the law. If you’re in the UK and need expert guidance, you can find the right accounting firm in East Anglia and other locations to help keep your business on track.
A good accountant doesn’t just handle taxes—they also help with budgeting, financial planning, and making smart business decisions. It’s an investment that can save you money (and stress) in the long run.
Mistake #3: Mixing Personal and Business Money
This is one of the biggest mistakes small business owners make. When business and personal finances get mixed together, it’s hard to keep track of what’s actually happening.
Imagine you buy something for your business but pay for it with your personal debit card. Then, you take money from your business account to cover a personal bill. Before you know it, things are messy, and you don’t really know how much your business is making or spending.
Fix it: Open a separate bank account for your business. Use it only for business-related expenses and deposits. This makes tracking your income, filing taxes, and budgeting much easier.
If you’re serious about keeping things organized, consider getting a business credit card, too. Just make sure you’re responsible with it—debt can become a problem fast if you’re not careful.
Mistake #4: Not Having a Budget
A budget isn’t just about cutting back on spending—it’s a plan for how you’ll use your money wisely. Without one, businesses often spend too much in some areas and not enough in others.
For example, maybe you’re putting a ton of money into marketing but not budgeting enough for inventory. Or you’re spending too much on office supplies but not investing in tools that could actually grow your business.
Fix it: Make a simple budget that covers:
- How much money you expect to make each month
- Your fixed costs (rent, internet, software subscriptions)
- Your variable costs (supplies, shipping, advertising)
- How much you’ll save for taxes and unexpected expenses
Once you have a budget, stick to it! Review it every month and adjust as needed.
Mistake #5: Taking on Too Much Debt
Sometimes, businesses need loans to get started or grow, but borrowing too much (or borrowing without a clear plan) can lead to serious trouble.
A business loan might seem like free money at first, but you have to pay it back—with interest. If your business isn’t making enough to cover the payments, debt can quickly spiral out of control.
Fix it: Before taking out a loan, ask yourself:
- Do I really need this, or is there another way to fund my business?
- Can I afford the monthly payments?
- Will this loan actually help my business grow?
If you do borrow, make sure it’s for something that will bring in more money—like equipment that helps you produce products faster, not just fancy office furniture.
Mistake #6: Not Preparing for Slow Seasons
Most businesses have ups and downs. Retail stores might make most of their money during the holiday season, while landscapers might be busiest in the summer. If you don’t plan for slow months, you could run out of cash when sales drop.
Fix it: Create a savings buffer. When business is good, set aside extra money to cover expenses during slower months. If you know certain times of year are always slow, plan ahead by running promotions or finding ways to bring in extra income.
Mistake #7: Avoiding Professional Help
Many small business owners try to do everything themselves, from marketing to bookkeeping to customer service. While that might work at first, it’s not a good long-term strategy.
Handling finances without experience can lead to expensive mistakes. Business owners might miss tax deductions, overpay on expenses, or even get into legal trouble by not filing paperwork correctly.
Fix it: Don’t be afraid to ask for help. Whether it’s hiring an accountant, a financial advisor, or even a business coach, getting expert advice can save time, money, and stress.
Final Thoughts
Managing money might not be the most exciting part of running a business, but it’s what keeps everything running smoothly. The good news? It doesn’t have to be complicated, so stay on top of your numbers, plan ahead, and don’t be afraid to ask for help when you need it.
The biggest mistake you can make is waiting until there’s a problem to start paying attention to your finances. A little effort now—whether it’s setting a budget, tracking expenses, or working with an accountant—can save you from major headaches down the road.
Small steps add up. Get into good financial habits now, and your business will thank you later.









+ There are no comments
Add yours